Risk & compliance
Payments risk and compliance: chargebacks, fraud, frozen accounts, KYC and KYB, trust and safety, and the rules platforms must follow.
All Risk & compliance articles
How do payment providers hold your money? Safeguarding explained
What happens to your money while a payment provider holds it: safeguarding, segregated accounts, EMI vs bank, provider failure and documents to ask for.
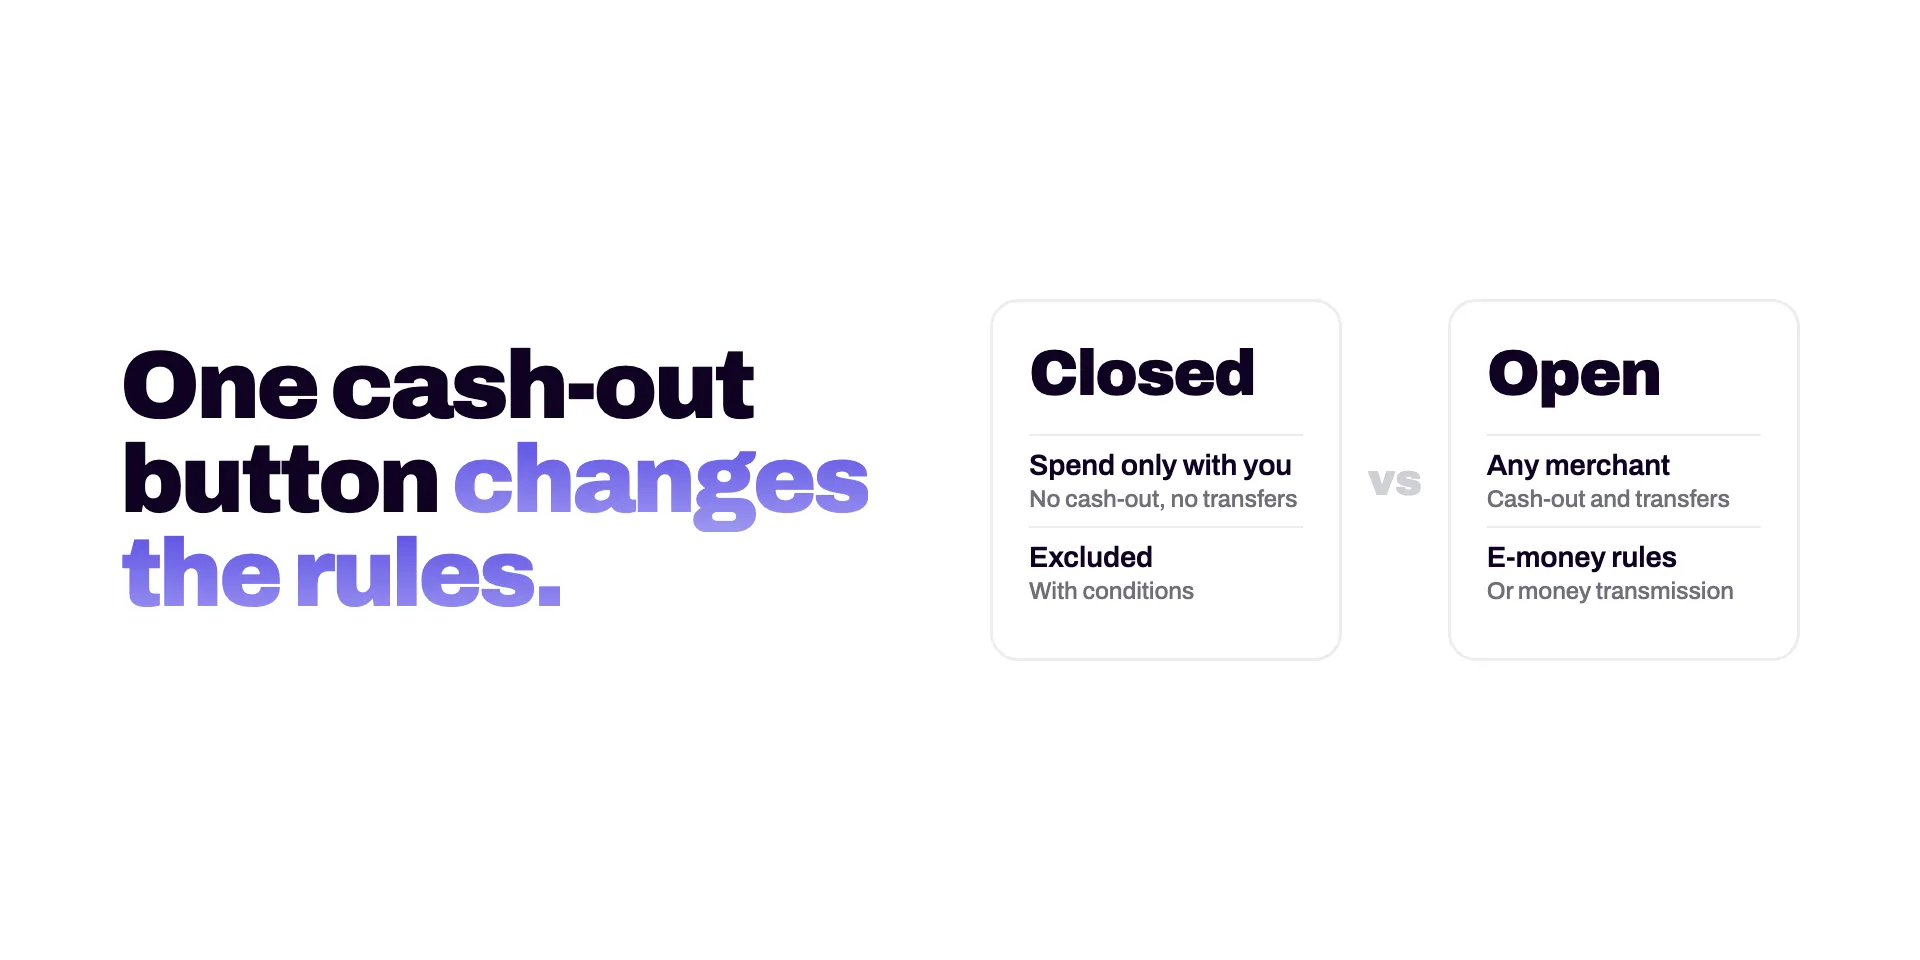
Are in-app credits regulated? Closed-loop vs open-loop virtual currency
When in-app credits become regulated stored value: closed-loop vs open-loop, the US prepaid access rule and the UK/EU limited network exclusion.
Why would a bank freeze a business account? The seven triggers
Banks freeze business accounts over AML flags, profile drift, cash patterns, document requests you missed, and court orders. The triggers, the process, the fixes.
Fintech with real support: why 'talk to a human' is a feature
When a platform holds your money, support quality is risk management. Why 'talk to a human' beats chatbots at the worst moment, and how to test it before you sign.
Payment processor holding funds on a large invoice
A processor holding funds on a large invoice is running a risk review. Why Stripe and PayPal hold big payments, how rolling reserves work, how to avoid it.
Bank blocked your customer's payment? The builder's fix
Banks decline $10k stage payments to trades as 'suspected fraud' — even in branch, with ID. Why it happens and how to stop it.
Payment platforms for freelancers who can't afford a freeze
Freelancer income looks like fraud to risk models: irregular, growing, cross-border. How to pick payment platforms — and structure — so a hold never hits rent.
7 reasons fintechs freeze business accounts — and how to avoid each
Frozen accounts almost never come out of nowhere. Here are the seven triggers that lock a fintech account, why each fires, and how to stay off the wire.
What to do if a fintech freezes your business funds
Frozen by your payment platform? A calm, step-by-step playbook to free your money fast — and how to set up so a hold can never take down payroll again.
The two-account rule: never keep all your money in one fintech
The best protection against frozen funds is structural: split money across a fast fintech and a chartered bank. Here is how the two-account rule works.
Where your money sits: a guide to fintech safeguarding
Is your fintech a bank? Is your money insured if it fails? A jargon-free explainer on safeguarding, partner banks, and who really holds your business cash.