Alternatives to Stripe Connect: 8 real options (2026)
Stripe Connect alternatives — Adyen, Fynex, Mangopay, PayPal, Rapyd, Airwallex, Dwolla, Trolley — compared on splits, payouts, held funds, KYC and fees.
 By Valeria VahorovskaUpdated 28 September 2026
Search “alternatives to Stripe Connect” and you’ll get a dozen listicles that all name the same five products and never tell you which one is for what. This is the version that does — the honest read on each real marketplace-payments option in 2026, and one thing most of the roundups miss: the rail you accept on and the layer that runs your money afterwards are two different decisions.
Connect is the reference point for a reason. It’s the most mature marketplace-payments product on the market, it’s what Shopify and DoorDash were built on, and if you’re accepting cards and paying one connected seller a flat platform fee, it’s hard to beat. So the useful question isn’t “is Connect good” — it’s “what makes a marketplace look elsewhere, and what does elsewhere actually offer.”
When you actually need an alternative
Marketplaces rarely leave Connect because it’s broken. They leave because they outgrow its shape. The triggers cluster:
- Multi-party splits. One checkout fans out to three sellers plus your commission plus a partner — and your fee logic is richer than a flat percentage (tiers, caps, a fixed listing fee, a referrer override). (We go deep on how splits actually work here.)
- Cross-border payouts. Your sellers are in different countries and currencies, and Stripe’s own rails aren’t the cheapest way to reach each one.
- Held funds and reserves. A review trips, the payout locks, and settlement money you were counting on sits inside an automated process for weeks.
- KYC drop-off. Sellers churn during onboarding before they’ve earned a penny, because full verification lands too early.
- Fee stacking. Per-active-account charges and payout fees add up as the roster grows.
If none of those bite, stay on Connect. If several do, here’s the field.
The alternatives, by what they’re good at
| Alternative | Built for | The trade |
|---|---|---|
| Adyen for Platforms | Enterprise marketplaces, multi-region, one serious processor | Heavy integration, sales-led |
| Fynex | The layer above the rail — splits, payout routing, reconciliation, run for you | Not a card acquirer; keep a pay-in rail underneath |
| Mangopay | Wallet-based, escrow-style flows, held funds in Europe | Infrastructure — your team assembles the flows |
| PayPal for Marketplaces / Hyperwallet | Buyer trust at checkout, mass payouts | Less unified developer experience |
| Rapyd | Local payment methods and payout corridors in many countries | A build, not a turnkey product |
| Airwallex | Multi-currency collection and cross-border payouts | Single-network economics |
| Dwolla | US account-to-account (ACH) flows | Deliberately not a card acquirer |
| Trolley | Payouts only, worldwide, tax forms built in | Pair it with any acquirer |
Adyen for Platforms — the enterprise choice. Built for marketplaces running high volume across multiple regions, with split payments via API, automated seller onboarding and KYC, and balance accounts that hold seller funds until payout. If you’re at scale and want one serious processor to consolidate on, this is the grown-up option. Reach and reliability are the draw; it’s not the lightest thing to integrate.
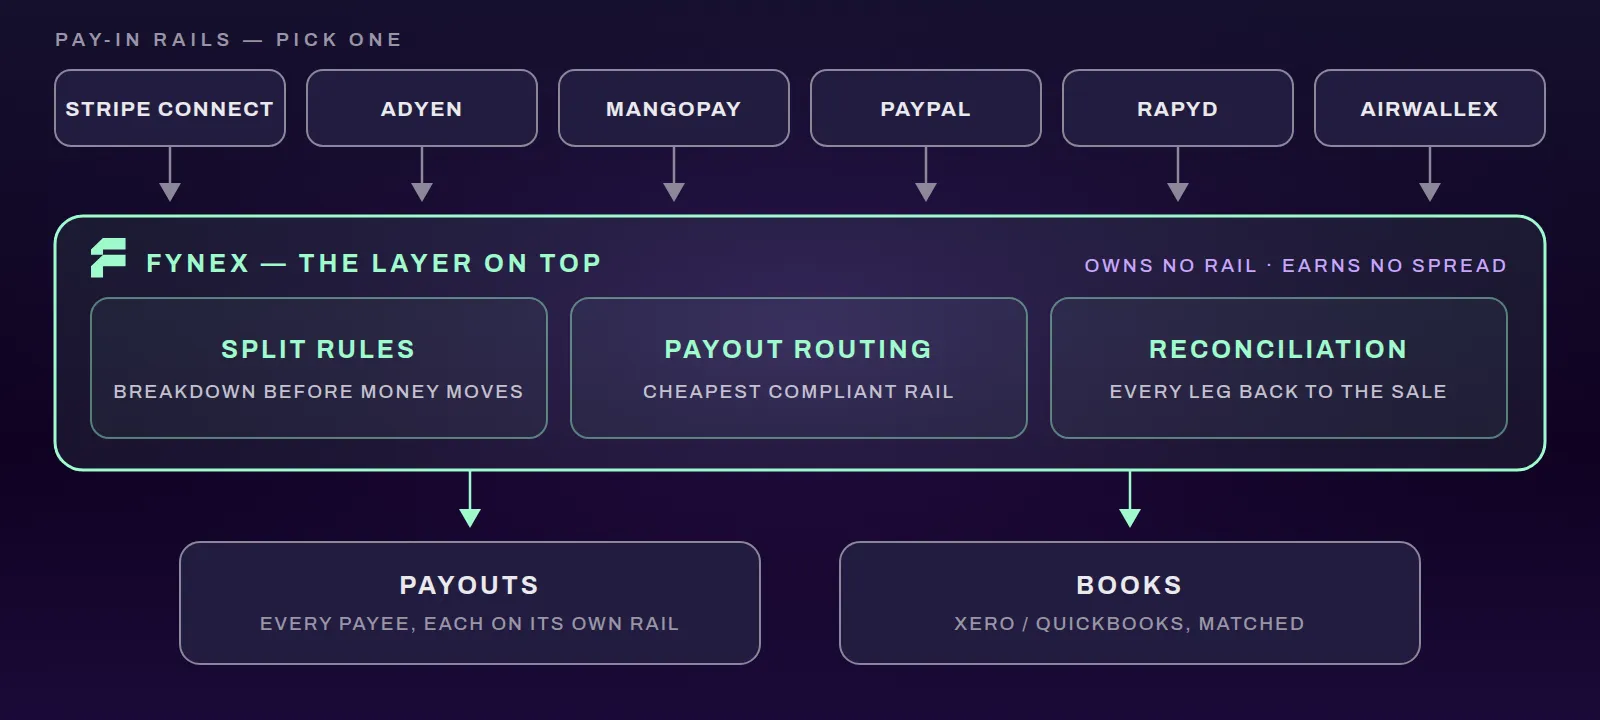
Fynex — the operating layer. For marketplaces where the split, the payout routing and the reconciliation are the actual problem rather than card acceptance. It runs multi-party splits as versioned rules, routes each payout to the cheapest compliant rail, and books every leg to Xero, QuickBooks or FreshBooks. You keep a processor underneath it for taking the card.
Mangopay — the wallet specialist. Purpose-built for marketplace and platform flows on an e-wallet model: funds land in digital wallets and you control timing, staged release and escrow-style logic across parties. It’s FCA-authorised as an e-money institution in the UK and PSD2-compliant across Europe, and it’s a common pick for European platforms that need to hold money, not just pass it through. Choose it when controlled disbursement and held funds are the core requirement.
PayPal for Marketplaces (with Hyperwallet) — the trust-and-payouts play. PayPal is one of the most widely adopted marketplace solutions for split payments, mass payouts and global reach, and Braintree suits consumer-facing platforms where PayPal recognition at checkout genuinely lifts conversion. Hyperwallet, its payout arm, is a dedicated mass-payout service for reaching many sellers or creators across countries. Strong on buyer trust and disbursement breadth; the developer experience is less unified than Stripe’s.
Rapyd — the local-methods and payout network. A global payment and payout infrastructure platform built for reach: local payment methods in many markets and payouts to sellers, creators and contractors across a wide spread of countries and currencies. Compelling when your problem is breadth of corridors — paying a lot of people in a lot of places — more than checkout polish.
Airwallex — the multi-currency operator. Collects in many currencies, makes payouts across 200+ countries and regions, and lets platforms collect, split and pay out cross-border from a multi-currency wallet without every seller needing PayFac registration. Settling in the same currency you collected avoids needless FX. A strong fit for platforms whose pain is genuinely multi-currency fund flow.
Dwolla — the US bank-transfer specialist. For US-only platforms moving money account-to-account, Dwolla does programmable ACH — cheap, reliable and unglamorous. If your flows are US bank transfers (B2B marketplaces, rebates, disbursements), it takes card economics out of the equation entirely. It is deliberately not a card acquirer, so it replaces the payout half of Connect rather than the checkout half.
Trolley — payouts at scale. Sometimes pay-in isn’t the problem: sellers are paid by the platform, and what you need is contractor networks, creator platforms or royalty flows paid out worldwide. Trolley (formerly Payment Rails) does global payouts with tax-form collection (W-9/W-8) built in, and pairs with any acquirer. If that’s your shape, also see the teardown of payout structures for home-services platforms.
And the newer marketplace-native processors — players like Ryft position specifically for European marketplace operators with PSD2 compliance, volume-based pricing and split payments to many sellers per transaction. Worth a look if you’re EU-focused and want something built for the marketplace case from the ground up rather than adapted to it.
Every one of these is a genuine option. The mistake is treating the choice as final — because none of them is the only decision you make about your money.
Where Fynex fits
Fynex runs the money after the rail has taken it. One payment splits across several payees, each payout leaves on the cheapest compliant rail, and every leg posts back to Xero or QuickBooks as a journal entry — not a CSV you re-key. For card acceptance itself it isn’t the answer: keep Connect, Adyen or Mangopay underneath.
That’s the distinction the listicles skip. Everything above is a rail — it accepts the payment and moves the money. What happens to that money afterwards is a separate decision, and it’s the one nobody shortlists for.
What people are actually trying to do when they get here
| The job | What happens |
|---|---|
| Reconcile Stripe payments in Xero | Every payment and payout posts as a journal entry, scored for confidence. PSP deposits are broken out and exceptions flagged with the reason attached. |
| Account for Stripe fees in Xero | The fee comes out of the gross deposit and posts separately, so the bank line and the invoice match without a manual adjustment. |
| Split one payment across several sellers | A split rule is a versioned object: lines to named payees, percentages, flat fees, caps and fill priority. Change one payee’s terms from the dashboard — not in a release. |
| Pay sellers in several countries | Each payout routes per corridor to the cheapest compliant rail — SEPA, SWIFT or local — rather than one provider’s network. |
| Pay vendors directly from QuickBooks | The connection posts both ways; what syncs is documented here. Xero and FreshBooks work the same way. |
Fynex doesn’t own payment rails, so it isn’t a drop-in Connect replacement for card acceptance. It’s the layer that runs the splits, the payout routing and the books on top of whichever rail you picked. Auto-invoicing, collections and cash forecasting sit around it.
The reason the routing is trustworthy: Fynex owns no rail and earns no spread on your flow, so the “which rail should this money take” decision is neutral — it optimises your cost, not Fynex’s revenue. And when you need cover, Fynex is an FCA-authorised e-money institution with client funds safeguarded, PCI DSS Level 1, and can act as Merchant of Record.
The one-liner: accounts hold money, rails move it, Fynex is the layer that thinks. Keep your processor. Put an operator on top of it.
Choosing
A quick decision map:
- Need to reconcile Stripe payments in Xero, pay sellers in several countries, and stop re-keying it every week? Keep Connect as the pay-in rail and put Fynex on top of it.
- High volume across many regions, want one enterprise processor? Adyen for Platforms.
- Need to hold funds, stage releases, run escrow-style flows — especially in Europe? Mangopay.
- Buyer trust at checkout and broad mass payouts matter most? PayPal for Marketplaces / Hyperwallet.
- Your pain is corridors — paying many people in many countries? Rapyd.
- Genuinely multi-currency collection and payout? Airwallex.
- US-only, account-to-account, no cards? Dwolla.
- Pay-in is fine; you need payouts and tax forms at scale? Trolley.
Then ask the second question every roundup forgets: once the rail has done its job, who runs the split, picks the payout route, and reconciles the books? If the honest answer is “a person with a spreadsheet on Friday,” that’s the layer Fynex replaces — on top of whichever rail you just chose.
Also worth reading: the compare hub for every head-to-head, how to pay out marketplace sellers for the schedules-and-rails decision underneath, and the split payment calculator to price your own split.
For the deeper Stripe-specific comparison, see Stripe vs Fynex.