Agentic finance vs expense management: the difference
Expense management agents approve and code card spend. Agentic finance runs the whole money chain: invoicing, payouts, reconciliation, cash. Side by side.
 By Valeria VahorovskaUpdated 29 September 2026
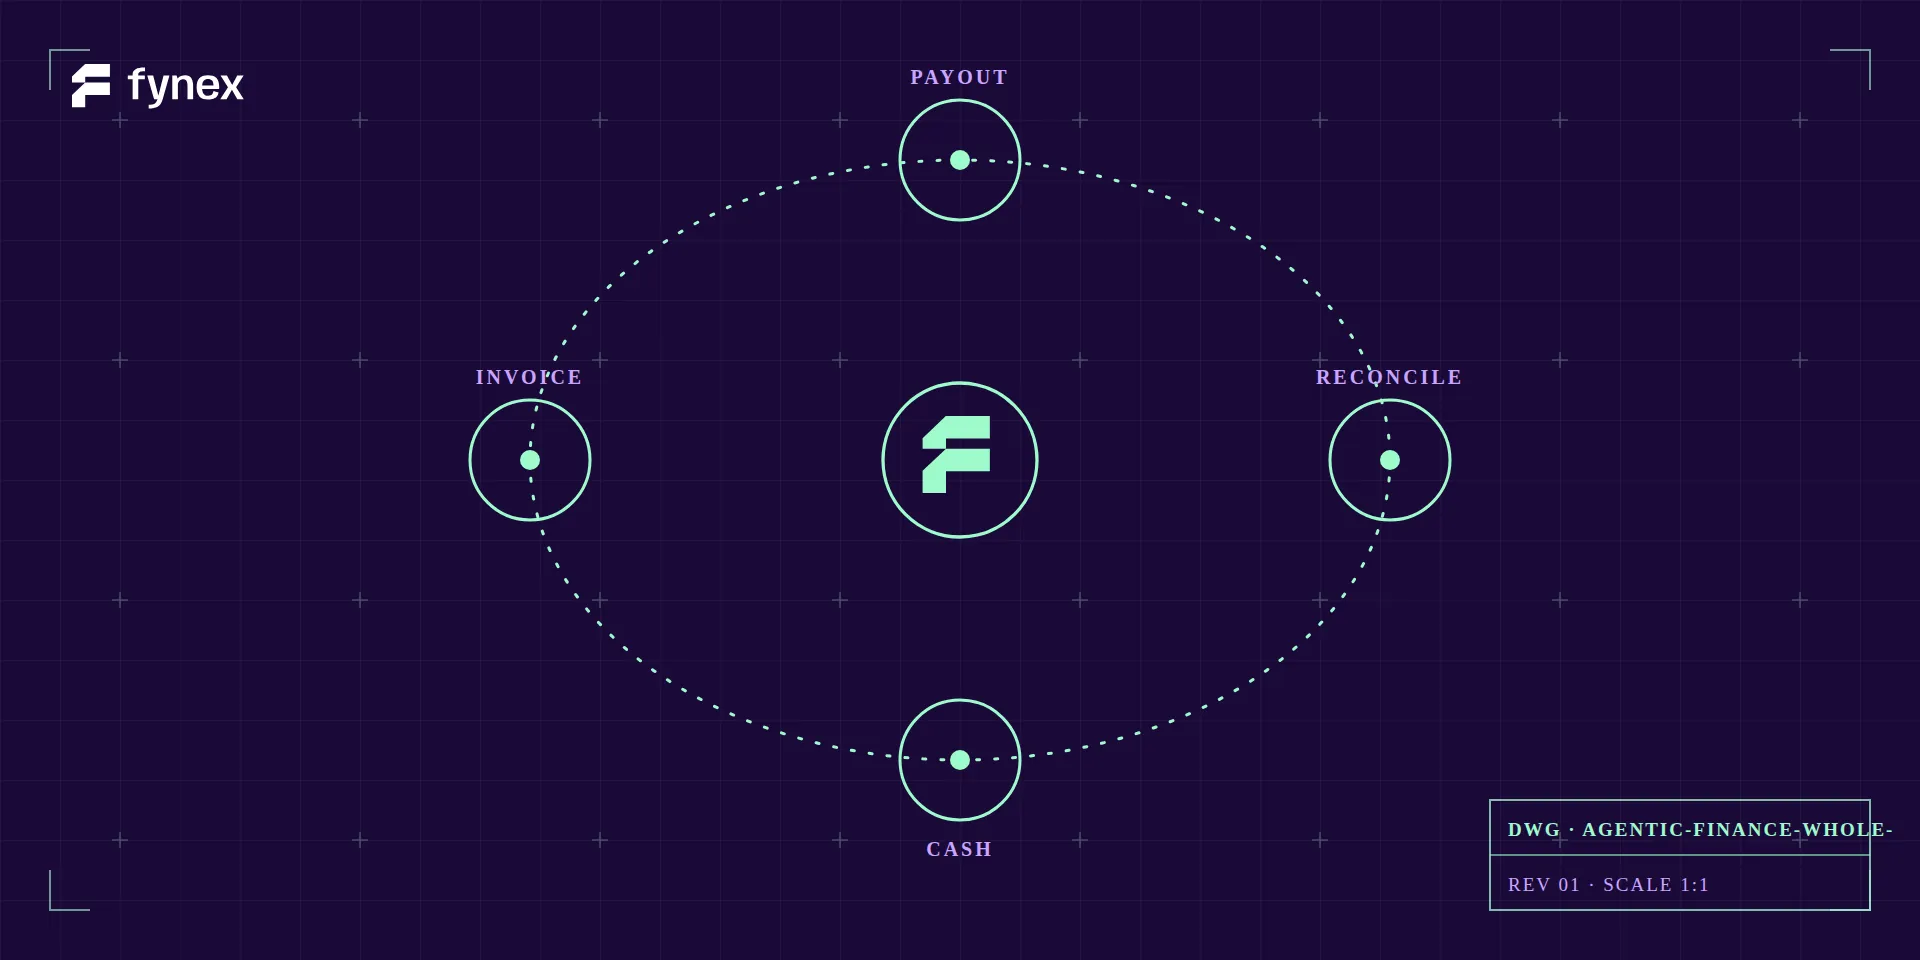
Agentic finance and expense management differ in scope. Expense management agents approve, audit and code card spend: money that has already left the business. Agentic finance runs the whole money chain: invoicing and collections, supplier and partner payouts, reconciliation, and cash forecasting. Agents prepare every decision across all four stages, and a person approves what moves money.
Two documents this year point the same way. The IMF’s How Agentic AI Will Reshape Payments maps the risks from a policy seat. Hui Gong’s Agent-to-Agent Finance maps the infrastructure from a research seat. Both conclude that agents in finance are real and valuable, and that their autonomy has to be bounded rather than maximised.
What neither is about, and what most of the market is stuck on, is scope. That is the argument here.
Key takeaways
- Most “agentic finance” is agentic spend. It works on card transactions that have already happened.
- The money chain has four stages. Money in, money out, money tied together, money looking forward.
- Scope is the first evaluation question. Ask how much of the chain a tool’s agents actually reach.
- The human belongs at settlement. Agents reason freely; the irreversible act waits for approval.
What is agentic finance?
Agentic finance is finance operations run by AI agents that act on the money chain under rules a human sets. The system executes the work rather than waiting for someone to drive it.
The one-line definition lives in our glossary. The practical test is simpler: does the next action arrive on its own, or do you still export a CSV and reconcile by eye? If you still drive the tool, it is software. How that differs from a SaaS stack is covered in agentic finance vs SaaS. This post is about a narrower confusion: agentic finance versus agentic expenses.
Agentic finance vs expense management, side by side
Expense management automates one corner of the finance function. Agentic finance covers every stage money passes through.
| Agentic finance (Fynex) | Expense management agents (Brex, Ramp) | |
|---|---|---|
| Money covered | In, out, reconciled, forecast | Card spend already made |
| Typical agent work | Raise and chase invoices, route payouts, match payments to invoices and POs, forecast cash | Approve expenses, audit against policy, code to the GL |
| Rails | The accounts, cards and payment providers you already hold | The vendor’s own cards |
| Where the human sits | Approves every movement of money | Card policy and approval rules decide which spend a person reviews |
| Question it answers | ”What happens next, and can we afford it?" | "Was this spend within policy?” |
Expense agents are real and useful. The honest Brex breakdown says as much. But notice what the right-hand column has in common: it’s all money that already left, on the vendor’s own card.
Why most “agentic finance” is agentic spend
Expenses are the easiest slice to make agentic because they are the most contained. The card sets the rails, the policy sets the bounds, and the money has already gone.
The adoption data shows the same pattern of slices. In its 2025 AI in Finance survey of 183 CFOs and senior finance leaders, Gartner found that 59% of finance leaders use AI in their finance function. The leading use cases were knowledge management (49%), accounts payable process automation (37%), and error and anomaly detection (34%). Each is one task, not a chain.
The label is also running ahead of the product. In June 2025, Gartner estimated that only about 130 of the thousands of agentic AI vendors are real, calling the rebranding of existing products “agent washing”. A good place to start is still a small place to stop.
The whole money chain, stage by stage
The money chain is every step money takes through a business. An operator lives inside all four stages at once.
- Money in. Invoicing and collections: raising invoices, chasing the ones that go quiet, collecting from clients across borders and currencies.
- Money out. Payouts: paying suppliers, contractors and partners across borders, routed and priced on whatever rail fits.
- Money tied together. Reconciliation: matching every payment to its invoice and PO into your ledger, catching mismatches and duplicates before they cost you.
- Money looking forward. Working capital and cash forecasting: how much cash you’ll have and when, and what that means for the next payout run.
Because the agents run all four stages on one reconciled record, the chain becomes readable: the real state of the business at a glance, continuously, not at month-end. Every stage is heavy on work agents do well: reading messy documents, matching records, chasing, forecasting, drafting. And every stage is reversible reasoning right up to the moment money moves.
The official framing points here too. The IMF note’s use cases include agents orchestrating the whole cross-border payment chain, from initiation and routing to compliance checks and settlement monitoring, plus liquidity and treasury management. That is the whole chain, not the expense corner of it.
A worked example: one agency, one month
Say you run an agency billing 30 clients $420,000 a month and paying 45 contractors $250,000. Team card spend is $14,000.
An expense agent reaches the $14,000: it approves the cards, checks the receipts and codes them. That is about 2% of the money moving through the business that month.
An agentic finance layer reaches the rest. It raises the 30 invoices and chases the six that go quiet. It prices and routes the 45 contractor payouts and holds the run until a person approves it. It matches each incoming payment to its invoice, flags the client who short-paid by $3,200, and forecasts whether cash covers next month’s run. The expense corner is still covered. It is simply not where the work is.
The two design questions that matter
Every agentic finance product answers two questions. Both papers, in their own vocabulary, say these are the ones to ask.
1. Which part of the money chain do the agents run? Ask how much of the chain a tool reaches, and be suspicious of “agentic finance” that turns out to mean “agentic expenses”. Our Fynex vs Brex comparison makes that scope difference concrete.
2. Where does the human sit relative to the money? The IMF frames it as the tension between probabilistic agents and deterministic settlement. Gong frames it as bounded autonomy. Same answer, two accents: let the agent reason freely, and bound its authority over irreversible money. Fynex draws that bound at settlement: agents prepare, the human approves what moves, because instant money is irrevocable.
What happens next
I’ve spent seventeen years in payments, and I built a payments business to $2B across eight European markets before this one. Here is where I’d bet.
Agent reasoning over the whole money chain becomes table stakes. Gartner predicts that at least 15% of day-to-day work decisions will be made autonomously through agentic AI by 2028, up from 0% in 2024. The finance function stops being data entry, chasing and manual matching.
Fully autonomous money movement arrives more slowly and more selectively than the demos suggest. The risks are systemic and the liability questions are unresolved. The winners won’t remove the human fastest. They’ll give agents the most reach over the reasoning and keep the firmest hand on the movement.
Related: intent, authorization, settlement is the mechanism underneath this, and know your agent is the compliance layer it has to satisfy.
That is the version we build, and the Fynex product is organised around it: the whole money chain, run by agents, with a human on the one boundary that’s final. Run your business, not your books. If money comes in from clients and goes out to many parties, as in an agency, a marketplace or a studio, the whole chain is what’s worth making agentic. The corner isn’t.